Request Your Free Quote!
What Insurance Pays for Drywall Before a Record El Nino Winter
Sudden leaks get paid, slow ones get denied. What OC homeowners insurance covers for drywall water damage, real repair costs, and deductible math.
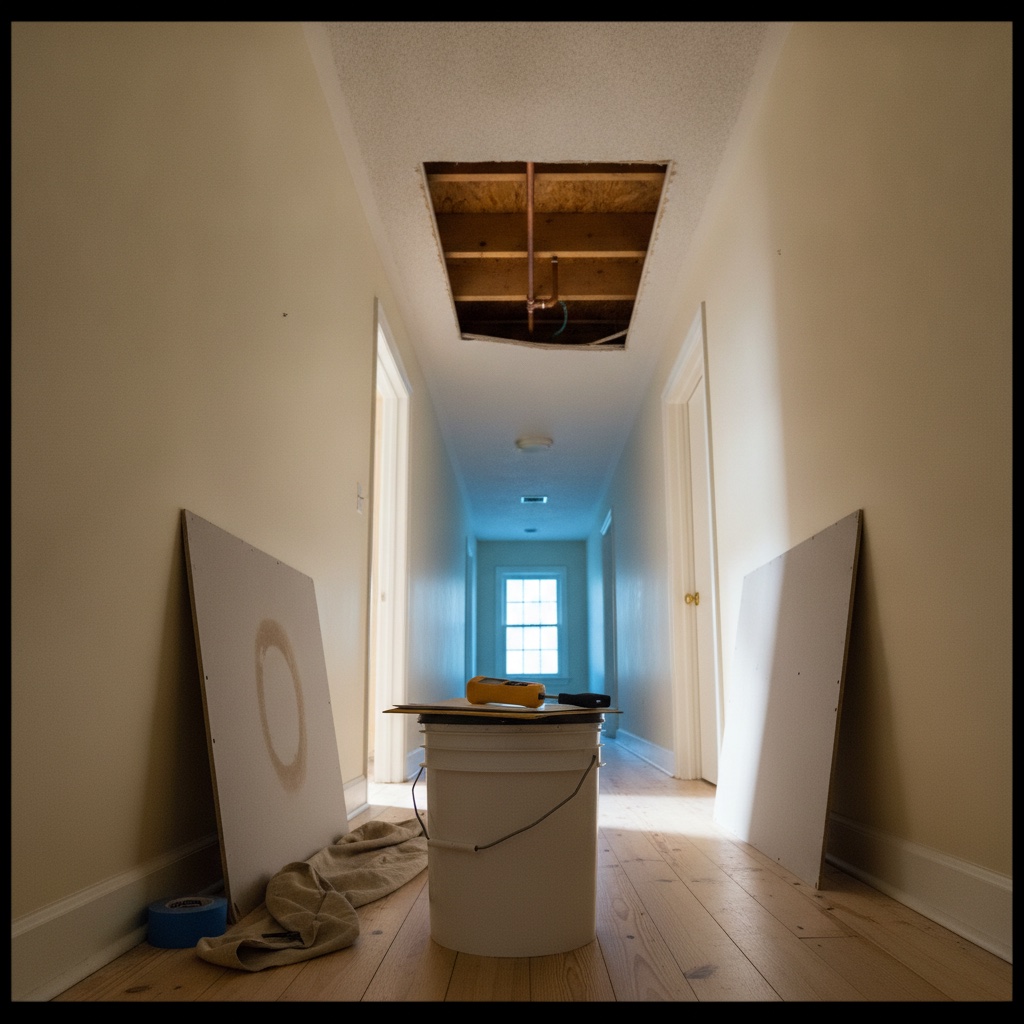
A supply line under a Huntington Beach bathroom sink lets go on a Saturday night in January. By Sunday morning the hallway ceiling below has a 30-inch brown bloom and a sag you can press with a broom handle. That claim almost always gets paid. Now picture the same stain, but caused by a roof flashing that has been weeping every storm since 2023. That one usually gets denied. With the state now bracing for a record El Nino winter, the difference between those two ceilings is worth understanding before the first storm, not after.
Why This Winter Changes the Math
The Climate Prediction Center’s September 10 update gives El Nino better than a 90 percent chance of becoming a very strong event this winter, with a 75 percent chance of setting a new record for October through December. Governor Newsom declared a state of emergency on September 21, and the Department of Insurance followed on September 22 with a plain warning: most homeowners policies exclude flood, mudslide, and debris flow, and flood coverage bought today will not start for 30 days. For Orange County homeowners, that means the time to read the policy is the next two weeks.
Water damage is already the most disputed claim type in the country. Insurance Business reported on September 2 that water claims carry roughly a 10 percent denial rate, the highest of any homeowners category, and the average paid water claim runs about $15,400. Most of those disputes turn on one word in the policy: sudden. Premiums are also climbing. The California FAIR Plan’s average 29.1 percent increase takes effect October 15, so plenty of homeowners are about to think twice before filing a small claim at all.
What the Carrier Usually Pays, and What It Won’t
A standard HO-3 policy is built to cover sudden and accidental water damage from a covered source. On the drywall side, the claims that usually get paid look like this:
- A burst or cracked supply line, toilet fill valve, or dishwasher hose that soaks a wall or the ceiling below.
- A water heater that ruptures in a garage and wicks up the firewall.
- Wind-driven rain entering through storm damage, such as shingles torn off in a gust or a tree limb through the roof.
- A fallen tree that punches through a ceiling.
The claims that usually get denied are the slow ones. A shower valve that has dripped behind tile for eight months, a roof that leaks a little every rain, a window with failed caulk, or a slab that wicks ground moisture into the bottom 12 inches of a wall. Carriers call that wear, tear, and deferred maintenance. Surface water flooding in from the yard falls under the flood exclusion, which needs a separate NFIP or private flood policy. Mold cleanup is often capped at a low sublimit, sometimes $5,000 or $10,000, so read that line on your declarations page before you need it.
Deductible Math on Real OC Drywall Repairs
Most Orange County homeowners carry a $1,000 to $2,500 deductible. Compare that with what the drywall portion of a water loss actually costs, and a lot of small claims stop making sense. Here are typical 2026 ranges for an OC home with an existing knockdown or orange peel texture, including texture match, primer, and paint on the repaired area:
- Small ceiling stain, board still sound, stain-block primer and repaint: $350 to $650.
- Cut out and replace a 4 by 8 foot ceiling section, retexture, prime, and paint: $900 to $1,600.
- Replace the full ceiling in a 12 by 14 foot bedroom, about 170 square feet, with texture match: $2,200 to $3,800.
- Flood cut the bottom 2 feet of walls in a 400 square foot family room, new board, level-4 finish, texture, and paint: $2,800 to $4,500.
For larger rebuilds, OC pricing for new hang, tape, and finish runs about $3.50 to $5.50 per square foot of board at a level-4 finish, and another $1.00 to $1.50 per square foot for a level-5 skim coat on smooth walls. If the drywall bill lands under or near your deductible, a claim adds a loss to your record for little or no payout. Above roughly twice the deductible, especially once you add plumbing, drying, insulation, and flooring, filing usually starts to pay for itself.
How a Water-Damage Quote Gets Built
Adjusters price drywall line by line, so a useful contractor quote should read the same way. A JNL water-damage quote spells out moisture readings and the cut line, demolition and haul-off of wet board and insulation, new board to match the existing thickness, whether that is half-inch or five-eighths Type X in a garage firewall, then tape, three coats, sanding, texture match, stain-blocking primer, finish paint, and site cleanup. Each line has its own quantity, which makes it easy for the adjuster to compare against their own estimate without guessing.
Texture match is where most claims get argued. California’s fair claims regulations call for repairs that leave the damaged area with a reasonably uniform appearance, so a patch that shows as a bright square in a knockdown ceiling is not the finish line. Common scope changes appear once the board comes off: wet batt insulation adds $1.50 to $3.00 per square foot to replace, and visible mold on the back of the paper adds containment and treatment, often $500 to $1,500 for a single room. Photograph everything before it goes in the dumpster, because the adjuster may not see the wall until after demo.
A Two-Week Prep List Before the Rain
Pull out your declarations page and find three numbers: the deductible, the mold sublimit, and whether water backup is covered by endorsement. Walk the house with a flashlight and a phone. Photograph every ceiling, every wall below a bathroom, and any existing stain, with a date stamp. A pre-storm photo that shows a clean ceiling is the best evidence you will ever have that a new stain is sudden rather than gradual. Old stains that are dry and stable should be sealed and repainted now, so they cannot be confused with new damage later.
If you already have a stain you are unsure about, this is the cheapest month of the year to find out what it is. A moisture meter reading costs nothing to take and tells you whether the leak is active. We offer a free in-home assessment across Orange County and north San Diego County, with moisture readings, photos, and a line-item quote you can hand straight to your adjuster or keep on file for the storms ahead. Book a visit before the calendar fills with the first real rain.
Morning-context sources used: NOAA Climate Prediction Center, “ENSO Diagnostic Discussion” (Sep 10, 2026), https://www.cpc.ncep.noaa.gov/products/analysis_monitoring/enso_advisory/ensodisc.shtml ; California Department of Insurance, “Commissioner Lara urges Californians to review insurance coverage before likely historic El Nino storms hit” (Sep 22, 2026), https://www.insurance.ca.gov/0400-news/0100-press-releases/release033-2026.cfm ; Insurance Business, “Water damage has the highest denial rate of any homeowners claim” (Sep 2, 2026), https://www.insurancebusinessmag.com/us/news/property/water-damage-has-the-highest-denial-rate-of-any-homeowners-claim–it-matters-for-every-client-588244.aspx ; The Weather Channel, “Flooding, fewer fires ahead: The time to shop for insurance is now” (Sep 14, 2026), https://weather.com/2026/09/14/safety/floods/california-el-nino-flood-insurance ; KQED, “California FAIR Plan Announces 29.1% Rate Hike for Homeowners This Fall” (Aug 11, 2026, updated Aug 24), https://www.kqed.org/news/12094860/california-fair-plan-announces-29-1-rate-hike-for-homeowners-this-fall